Never declared your crypto for several years? The route, how many years HMRC asks for, and what it costs
Published 12 November 2026 Reviewed against gov.uk 12 November 2026 10 min readHMRC and compliance
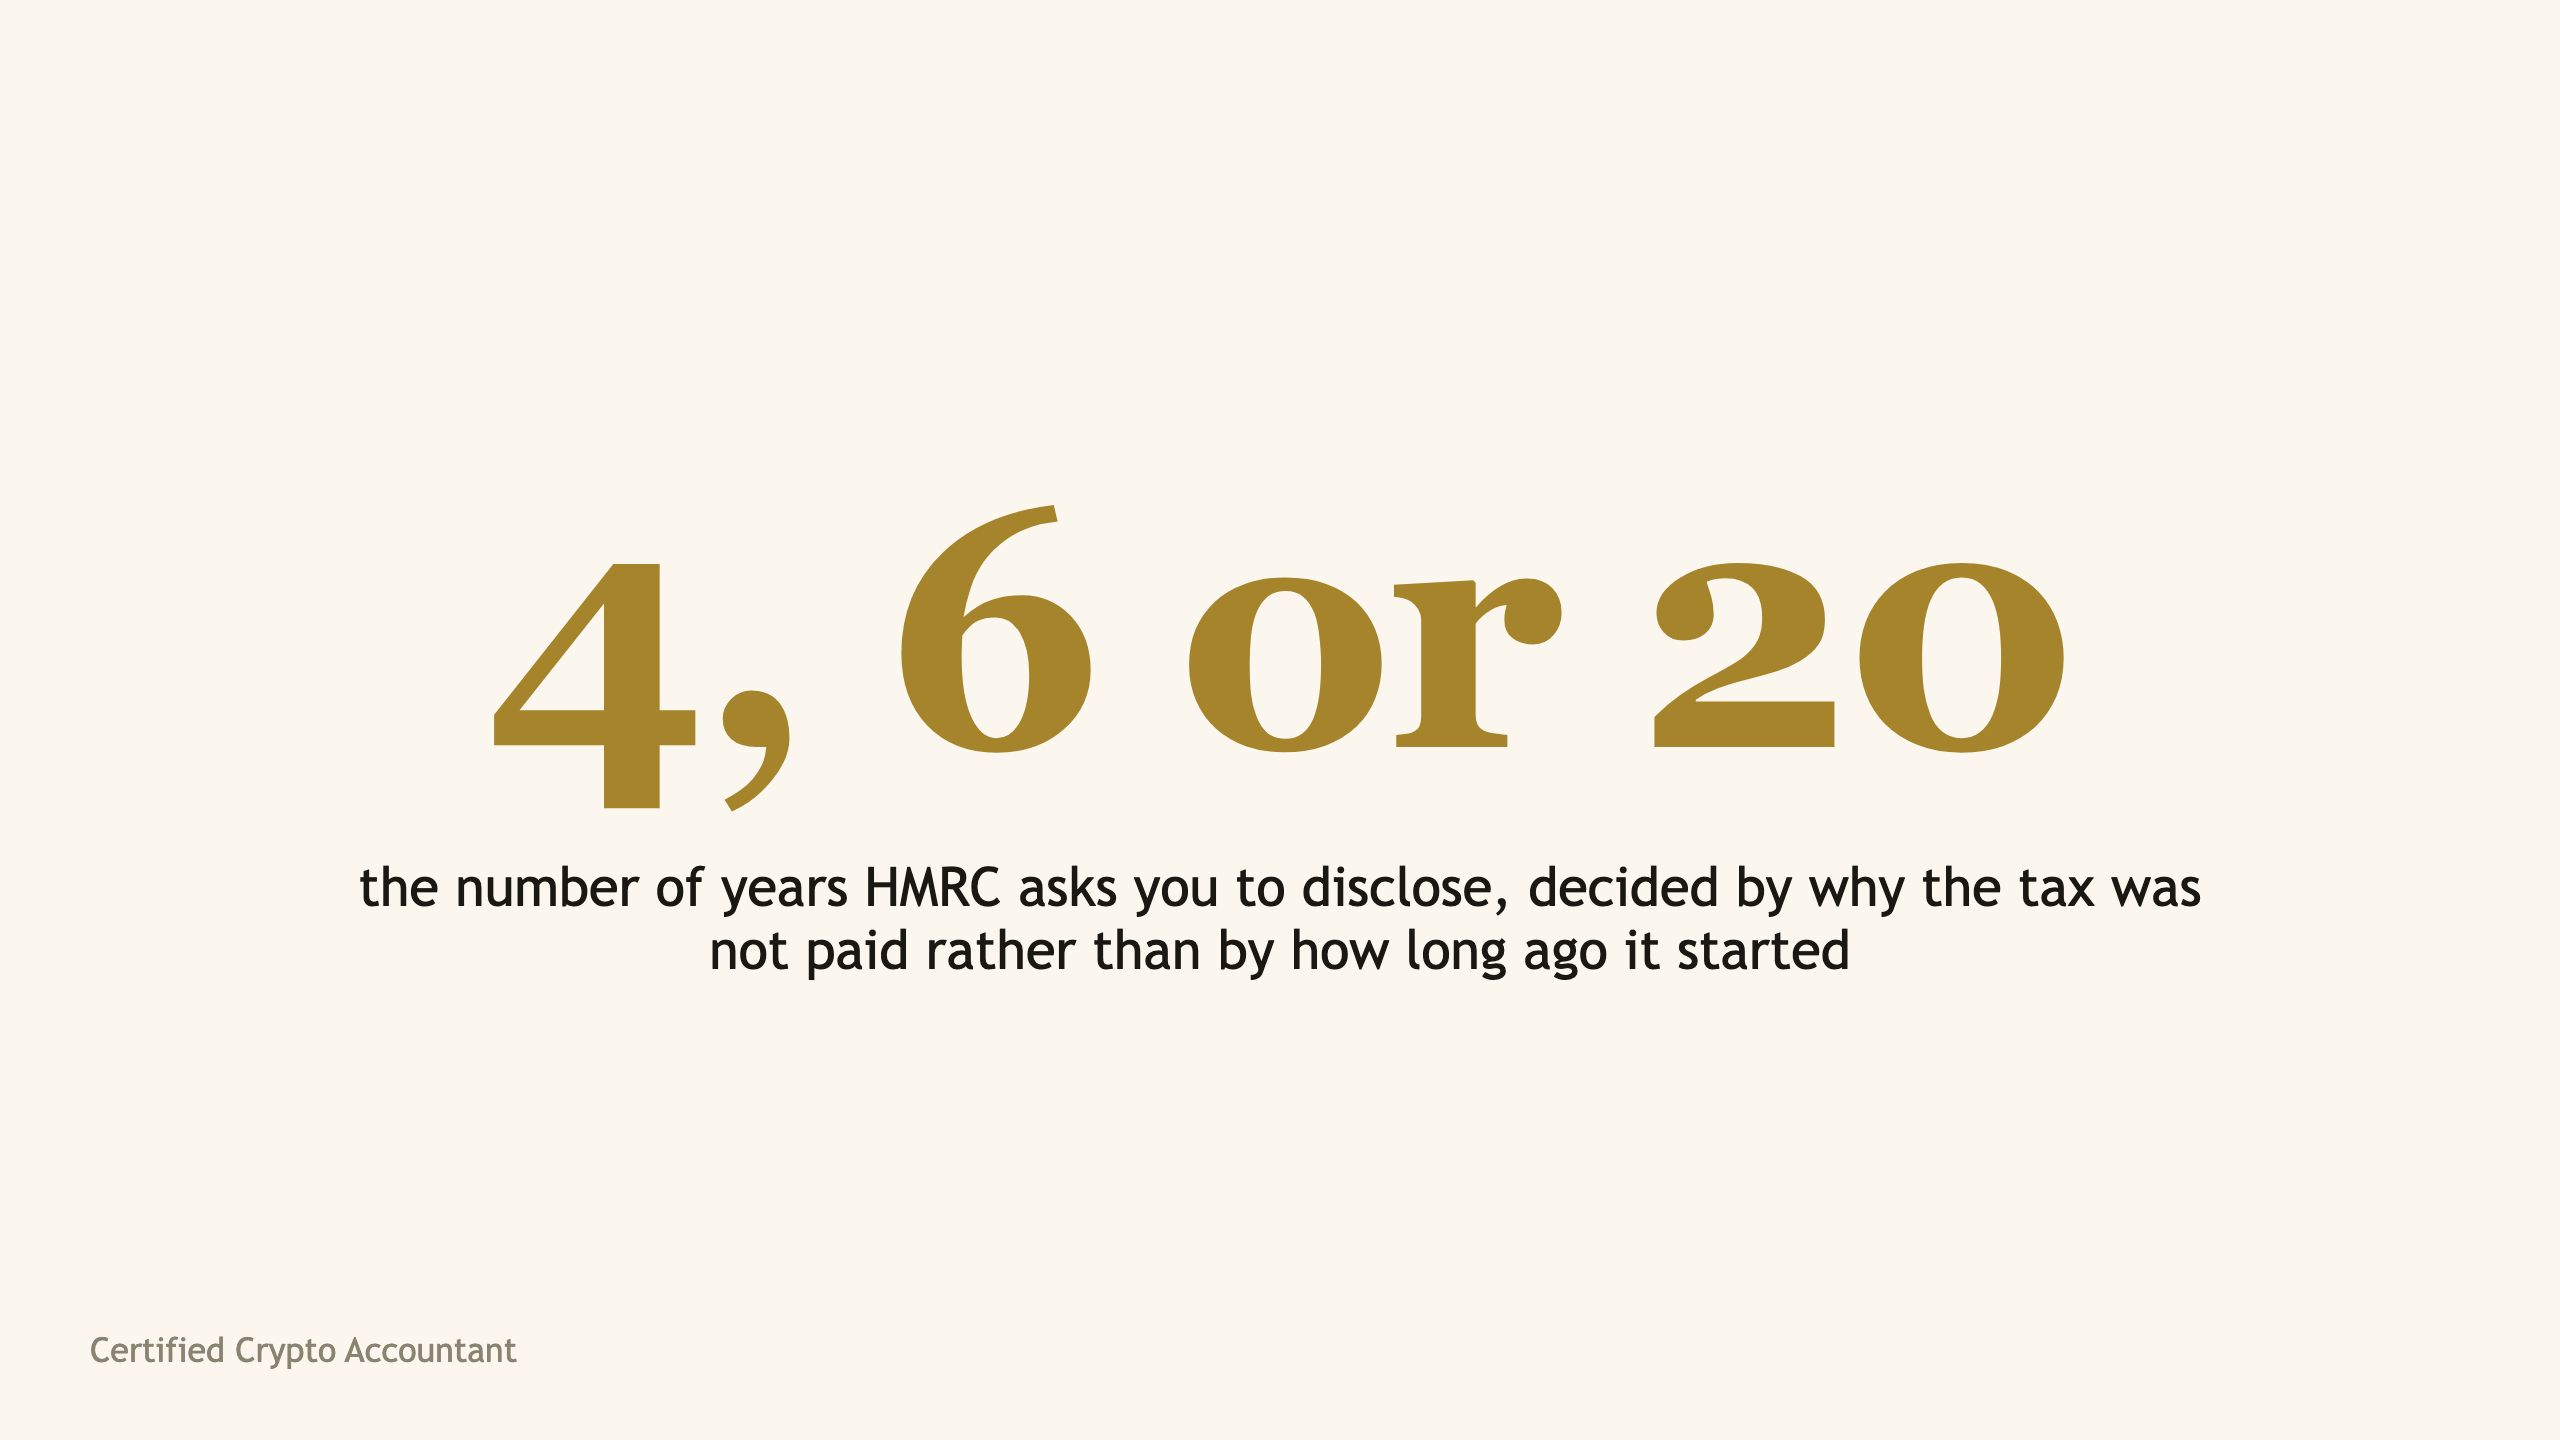
If you have never declared your crypto, the route is HMRC’s cryptoasset disclosure service for the older years and a Self Assessment return for the most recent one. How many years you go back depends on why the tax was not paid rather than on how long ago you started. You work out the gain for each year, the tax, the interest and a penalty you propose yourself, submit the lot, and pay within 30 days.
That is the whole shape of it. The rest of this page is the detail, in the order you will meet it.
Never declared crypto for several years. The year to 5 April 2026 goes on a Self Assessment return by 31 January 2027, and everything older goes through HMRC’s cryptoasset disclosure service, four years in total if you took reasonable care, six if careless, twenty if deliberate. Go before HMRC writes and the penalty range is lowest. Rebuild the history first, because the computation is the disclosure, and remember the early years were often below the £12,300 allowance.
First, the years that owe nothing
Capital Gains Tax is only due on gains above the annual exempt amount, and the allowance was large until recently. The published rates and allowances give £12,300 for 2021 to 2022 and 2022 to 2023, £6,000 for 2023 to 2024 and £3,000 from 2024 to 2025. A year in which your total gains across everything, crypto included, were below that figure has no tax to disclose, and with no tax there is no interest and no penalty for that year. Someone who traded modestly from 2020 and only did well in 2024 often finds that the first two or three years were never taxable at all.
Income is different. Staking rewards, lending interest, mining and airdrops taxed as income have no annual exempt amount of their own, only the trading and miscellaneous income allowance of £1,000 a year. The staking guide covers which rewards are income. Work out both sides for each year before deciding which years are in.
How many years HMRC asks for
Gov.uk’s guidance on the service ties the number of years to behaviour. If you took reasonable care, you disclose four years in total, the three years before the current one plus the current year reported correctly. If you did not take care, the maximum is six years, the five before the current one. If it was deliberate, which the page defines as knowing you owed tax but choosing not to tell HMRC, the maximum is twenty.
The statute behind that is the Taxes Management Act 1970. Section 34 allows an assessment within four years after the end of the tax year. Section 36 extends that to six years where the loss of tax was brought about carelessly and to twenty years where it was deliberate, or where it is attributable to a failure to notify chargeability under section 7. HMRC’s Compliance Handbook at CH53900 says the twenty year limit applies to a failure to notify whether or not the failure was deliberate, unless you had a reasonable excuse and put it right without unreasonable delay once the excuse ended. So someone who was never in Self Assessment at all should know that the law allows HMRC to go back twenty years in principle, even though the service asks for years by behaviour. In practice the question is settled by the years that actually owe tax, and in most files those are recent.
For a disclosure made this month, the current year is 2026 to 2027 and the previous year is 2025 to 2026. Gov.uk says income or gains from the current or previous tax year go on your Self Assessment return instead of through the service. Reasonable care therefore means the service covers 2023 to 2024 and 2024 to 2025, with 2025 to 2026 on a return. Carelessness adds 2021 to 2022 and 2022 to 2023 to the service, and for most people those two years fall below the £12,300 allowance anyway.
The year that goes on a return
The year to 5 April 2026 is declared on a Self Assessment return due by 31 January 2027. If you were never registered, the deadline to tell HMRC you needed to be was 5 October 2026, and the page on missing that date sets out what happens now, which is to register anyway, file by 31 January, and pay by the same date. The registration takes a few minutes online and the activation code arrives by post.
If you were in Self Assessment and filed returns that left the crypto out, the 2024 to 2025 return can still be amended rather than disclosed. Gov.uk says you can correct a return within 12 months of the Self Assessment deadline, so for 2024 to 2025 that is by 31 January 2027. Older filed years go through the service as inaccuracies rather than as a failure to notify, and the inaccuracy factsheet CC/FS7a applies to them.
What the service asks for
You sign in with a Government Gateway account, and gov.uk lists what the form needs before you start. Your personal details and National Insurance number. The number of transactions. The undeclared proceeds or income for each year before costs. The acquisition costs and expenses. The gains or profit with the calculations behind them. The exchanges used. The number of cryptoassets disposed of. The tax and interest owed with the calculations. And which commercial calculator was used, if any.
So the history has to be rebuilt first, every exchange, wallet and chain, pooled under HMRC’s share pooling rules for each year, with the sterling value on the day of every disposal. CRYPTO10400 says exchanges may keep records only for a short period or may no longer exist, and that the onus is on you. The page on closed exchanges and the page on getting a full history cover where the records still live.
Interest is calculated by you, per year, from the date each year’s tax was due, and gov.uk warns that if the interest figure is wrong HMRC will reject the disclosure. The penalty is also proposed by you, using the factsheets, with a box to explain why you chose it. The page says HMRC will check whether the penalty is fair and, if it thinks the figure is too low, may check your wider tax affairs.
The penalty you propose
For years in which you were never registered, the penalty is for failure to notify and the ranges are in CC/FS11, updated 19 March 2026. For a non deliberate failure disclosed unprompted, 0% to 30% of the tax if you tell HMRC within twelve months of the tax becoming due, and 10% to 30% after that. Prompted, 10% to 30% and 20% to 30%. Deliberate, 20% to 70% unprompted and 35% to 70% prompted. Deliberate and concealed, 30% to 100% and 50% to 100%. No penalty is due for a non deliberate failure where you had a reasonable excuse.
Unprompted is the word that decides which column you are in. The factsheet says a disclosure is unprompted if you tell HMRC before you had any reason to believe HMRC was about to find the failure. A nudge letter already in your hands makes the disclosure prompted. The guide to the nudge letter covers the position once one has arrived.
Within each range, the reductions are for telling, helping and giving access to records, and the quality of the disclosure is what moves the figure towards the bottom of the range. A disclosure that comes with the full computation, the pooled schedules and the bank reconciliation is the one that earns the reduction.
A worked example with figures
Suppose you started buying in 2020, never registered for Self Assessment, and your gains across everything were £4,000 in 2021 to 2022, £2,000 in 2022 to 2023, £9,000 in 2023 to 2024, £5,000 in 2024 to 2025 with every disposal after 30 October 2024, and £1,500 in 2025 to 2026. You are a basic rate taxpayer and nothing prompted you.
The first two years are below the £12,300 allowance and owe nothing. In 2023 to 2024 the allowance was £6,000, so £3,000 is taxable at the 10% rate that applied to disposals in that year, £300. In 2024 to 2025 the allowance was £3,000, so £2,000 is taxable at 18%, £360. In 2025 to 2026 the gain is below the £3,000 allowance, and that year goes on a return rather than through the service, showing no tax due. The disclosure covers 2023 to 2024 and 2024 to 2025, £660 of tax, plus interest from 31 January 2025 and 31 January 2026 respectively, plus a penalty within the 10% to 30% non deliberate unprompted range, £66 to £198, before HMRC’s own view of your behaviour and the reductions for a full disclosure.
If HMRC concluded you were careless rather than careful, the years asked for stretch to 2021 to 2022, and the figures do not change, because those years owe nothing. That is the usual pattern. The behaviour question decides how many years are listed far more often than it decides how much is paid.
The steps in order
One. Rebuild the history for every year, before anything is sent. Every platform, every wallet, every chain, including the ones that have closed. The computation is the disclosure.
Two. Decide which years are in. Work out the gain and the income for each year and compare it with that year’s allowance. Then apply the behaviour test honestly, and write down why you landed where you did.
Three. Register for Self Assessment and file the year to 5 April 2026 by 31 January 2027. If a 2024 to 2025 return was filed without the crypto, amend it by the same date instead of disclosing that year.
Four. Submit the disclosure for the older years with the tax, interest and proposed penalty, and keep the calculations. HMRC writes with a payment reference, and gov.uk says to call if nothing has arrived within 15 working days.
Five. Pay within 30 days of submitting. If you cannot, gov.uk says to call the helpline on 03000 55 22 94 to discuss options rather than let the deadline pass.
When it needs an accountant
One exchange, two years and gains that you can read off a single report is something you can take through the service yourself, and the free review will tell you whether the report is right first. It becomes a job when the history runs across several platforms and years, when exchanges have closed and costs have to be rebuilt or estimated, when income and gains both arise, when the behaviour question is not obvious, or when a letter has already arrived and the disclosure is now prompted. A multi year rebuild with a disclosure is the staged engagement below, half at signing, with the second stage priced once the first is done. An agent can submit the disclosure for you with a temporary authorisation, and we do.
Three fixed fees, quoted in writing before any work starts
One taxpayer, one tax year unless the line says otherwise. Written position within 15 working days of software access.
For an exchange-only history under about 5,000 trades where the software report is already built.£499
For several platforms, wallet transfers read as sales, duplicates, and one or two back years.£950
For DeFi, derivatives, high volume, or balances that do not tie.£1,750
Send your software report to zar@certifiedcryptoaccountant.com for a written fee the same working day, or start with the free review. Licensed and regulated by the AAT, licence 1010475.
Questions about declaring crypto after several years
I have never declared any crypto. Where do I start?
With the history, not the form. Rebuild every year from every exchange, wallet and chain, work out the gain and income for each year and compare it with that year's allowance. Then register for Self Assessment for the year to 5 April 2026 and put everything older through HMRC's cryptoasset disclosure service on gov.uk.
How many years do I have to go back?
Gov.uk ties it to behaviour. Four years in total if you took reasonable care, meaning the three years before the current one. Six if you were careless. Up to twenty if it was deliberate, which it defines as knowing you owed tax and choosing not to tell HMRC. The law allows twenty years where a person was never notified for Self Assessment at all, but the years that actually owe tax are usually the recent ones.
Will I owe tax for the early years?
Often not. The annual exempt amount was £12,300 in 2021 to 2022 and 2022 to 2023, so gains below that carry no tax, interest or penalty. It fell to £6,000 for 2023 to 2024 and £3,000 from 2024 to 2025, which is where most undeclared years start to owe.
What penalty will I pay?
For years you were never registered, HMRC's factsheet CC/FS11 puts a non deliberate failure disclosed unprompted at 10% to 30% of the tax once it is more than twelve months late, 20% to 30% if HMRC prompted you, 20% to 70% if deliberate. You propose the figure in the disclosure and explain it, and the quality of what you send moves it towards the bottom of the range. There is no penalty where you had a reasonable excuse.
Is it still unprompted if I have had a letter?
No. The factsheet says a disclosure is unprompted only if you make it before you had any reason to believe HMRC was about to find the failure. A nudge letter about cryptoassets makes the disclosure prompted and the range starts at 20% rather than 10%. It is still worth making, and quickly, because the range is wider still once HMRC opens a check.
Can an accountant submit the disclosure for me?
Yes. Gov.uk says an agent can submit on your behalf with a temporary authorisation to deal with your tax. The computation still has to be built from your records, and the declaration is yours.
Sources
Every figure on this page was checked against the source below on 12 November 2026.
- Tell HMRC about unpaid tax on cryptoassets. HM Revenue and Customs, checked 12 November 2026
- CC/FS11, penalties for failure to notify. HM Revenue and Customs, checked 12 November 2026
- CC/FS7a, penalties for inaccuracies in returns or documents. HM Revenue and Customs, checked 12 November 2026
- CH53100, assessing time limits, overview. HM Revenue and Customs, checked 12 November 2026
- CH53900, extended time limits, failure to notify. HM Revenue and Customs, checked 12 November 2026
- Self Assessment tax returns, if you need to change your return. GOV.UK, checked 12 November 2026
- Register for Self Assessment. GOV.UK, checked 12 November 2026
- Capital Gains Tax rates and annual tax-free allowances. HM Revenue and Customs, checked 12 November 2026
- CRYPTO10400, record keeping. HM Revenue and Customs, checked 12 November 2026
- Taxes Management Act 1970, section 7. legislation.gov.uk, checked 12 November 2026
- Taxes Management Act 1970, section 34. legislation.gov.uk, checked 12 November 2026
- Taxes Management Act 1970, section 36. legislation.gov.uk, checked 12 November 2026
Fahad Zar
Crypto tax accountantAAT licensed 1010475
- AAT Licensed Accountant and MAAT, licence 1010475
- MSc Accounting and Finance, BPP University London
- Six years inside digital asset accounting, across several crypto tax firms
- Practises through Zar Enterprises Ltd, ICO registration ZC225094
- Supervised for anti-money laundering by the AAT
What matters to me is that the number on the return is true, whatever it turns out to be.
Whether this is worth a conversation
Where this stops being a reading job and starts being a hiring one.
- Several years across more than one platform, with exchanges that have closed and costs that have to be rebuilt or estimated
- Income and gains both arise, or the behaviour question is not obvious and the number of years turns on it
- A letter from HMRC has already arrived, so the disclosure is prompted and the reply has a date on it
If it is one exchange, two recent years, and the gains read straight off a report that the free review confirms is right, you can take it through the service yourself. Register for the current year, submit the older years with the calculations, and pay within 30 days.
If one of these is you, the first look costs nothing.
Read next
Disclosing crypto tax to HMRC
The behaviour bands, the penalty table and how a disclosure is put together.
Reviewed 12 November 2026Deep guideHow HMRC's Digital Disclosure Service works
The general service for non crypto income, and where the crypto service differs.
Reviewed 12 November 2026DeadlineMissed the 5 October deadline to register
What it costs and what to do before 31 January 2027.
Reviewed 12 November 2026ExplainerHow far back HMRC can go
The four, six and twenty year limits in the Taxes Management Act.
Reviewed 12 November 2026 ExplainerHMRC's letter says you have disposed of cryptoassets. What it is, the 60 days, and what to send back
If the letter has already arrived, the disclosure is prompted. What the letter asks, the date, and the reply that keeps the penalty at the bottom of the range.
Reviewed 12 November 2026ExplainerHMRC's 2026 crypto letter has no deadline. What it says, why you got it, what to check before doing nothing
If the letter that arrived has no deadline and says no action is needed, it is the 2026 one. What it says, and why the disclosure is still prompted.
Reviewed 14 November 2026