Fixing a crypto tax report costs £499, £950 or £1,750, and the look that decides which one is free
Published 11 November 2026 Reviewed against gov.uk 11 November 2026 10 min readCrypto Tax
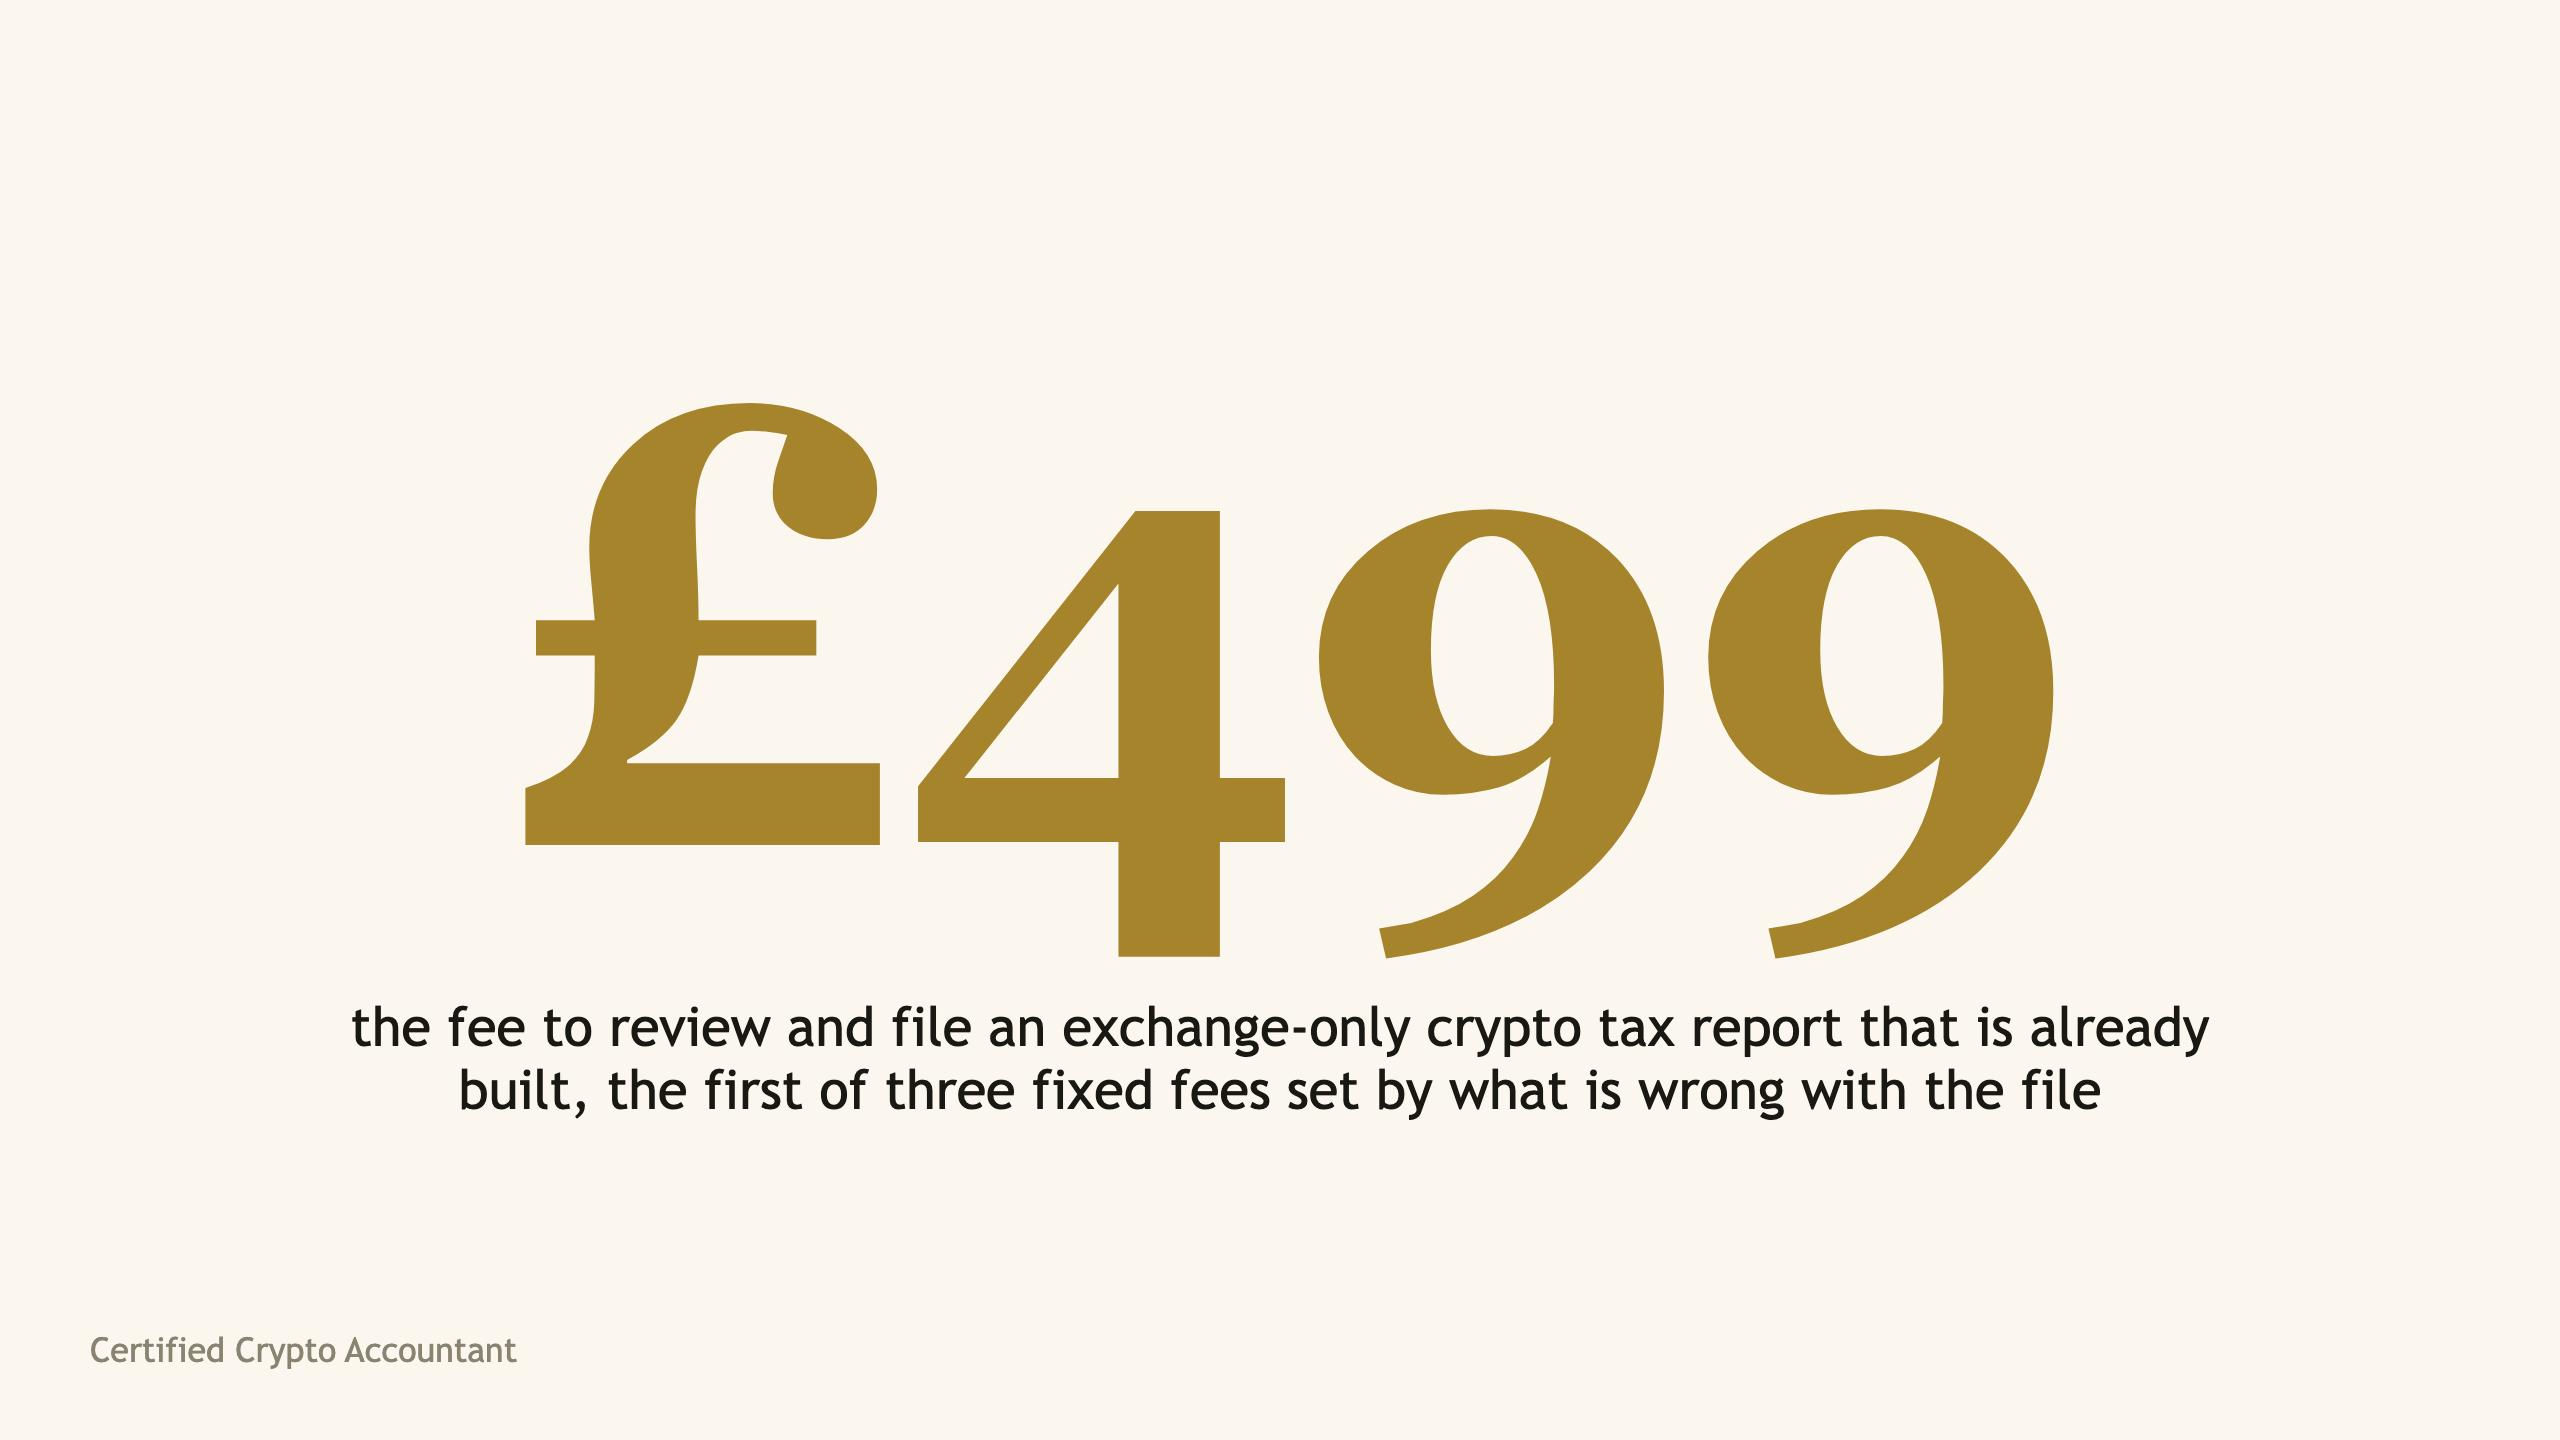
Fixing a crypto tax report costs £499, £950 or £1,750, and which of the three you pay is decided by what is wrong with the report rather than by how much tax is at stake. The look at your report that decides which of the three applies is free, and the fee is fixed and put in writing before any work starts.
That is the whole answer for one taxpayer and one tax year. The rest of this page is what moves a file from one fee to the next, what each fee buys, how to tell which one is yours in ten minutes, and when you need nobody at all.
Three fixed fees, £499, £950 or £1,750, set by how many platforms, unmatched transfers, nil costs, protocol positions and back years are in the report, never by the tax at stake. The look that decides which one is free, the fee is written down before any work starts, and if the report is already right there is no fee.
Five things decide the fee, and the size of the gain is none of them
The fee is the number of places the matching behind the report has to be repaired by hand, and five things drive that number.
One. How many platforms and chains are in the file. One exchange connected by API gives a history the software can read end to end. Three exchanges, two wallets and a chain the tool was never shown give movements with one end out of sight that a person has to pair. The count of sources is the first thing that lifts a report from £499 to £950.
Two. Transfers that do not match. HMRC’s Cryptoassets Manual at CRYPTO22100 says there is no disposal if you retain beneficial ownership of the tokens throughout, and gives moving tokens between public addresses you control as its example. Where a receiving wallet was never added, or the quantity differs by a network fee, the outgoing side is recorded as a sale and a gain appears that never happened. The guide to moving crypto between wallets explains the test.
Three. Disposals with a cost of nil. When the software never saw you buy a coin it watched you sell, it prices the coin at nil and the whole sale becomes gain. CRYPTO22150 allows the consideration in pound sterling originally paid for the asset plus the transaction fee for putting it on the distributed ledger, so the real cost has to be rebuilt from your own records. The page on the missing purchase history warning shows where it hides. Two nil costs on one exchange are an evening. Forty across a closed platform are a computation.
Four. DeFi and derivative positions. A liquidity pool entry, a wrapped token, a perpetual or a lending position is a chain of disposals and acquisitions no exchange export describes, and CRYPTO22200 puts every token of one type into a single pool under section 104 of the Taxation of Chargeable Gains Act 1992, after the same day and 30 day matching rules in section 106A. Working out which token was disposed of at each step, and at what sterling value, is the work that takes a report to £1,750.
Five. Back years. Pooling runs from the first purchase, so a wrong cost in 2021 changes the gain on every sale since. One or two earlier years sit within the £950 computation. Several years, an HMRC letter or a return that was never filed is the staged rebuild from £3,450, because the first stage has to be done before the second can be priced honestly.
What each fee includes, and what it does not
Review and file, £499. For an exchange-only history under about 5,000 trades where the software report is already built. The report is read against the exports, the settings, transfers and nil costs are tested, the position is written up and the return is filed. It does not include adding wallets the software was never given or rebuilding costs from a closed platform.
Computation, £950. For several platforms, wallet transfers read as sales, duplicates, and one or two back years. Every unmatched transfer is paired, doubled trades are removed, each nil cost is rebuilt, the pools are recomputed and the return is filed. It does not include DeFi positions, derivatives, or a file whose balances still will not tie.
Reconciliation, £1,750. For DeFi, derivatives, high volume, or balances that do not tie. The whole history is rebuilt transaction by transaction into a record you could hand to HMRC in an enquiry, with the pooled cost behind every disposal. The reconciliation service page describes that record. It does not include several unfiled years with an HMRC letter attached, which is the staged rebuild.
All three cover one taxpayer and one tax year unless the line says otherwise, all three are UK tax only, and all three end in a written position within 15 working days of software access.
How to tell which fee is yours in ten minutes
Open your report and take four counts. The sources connected, where one exchange alone points to £499 and three or more platforms or any wallet address points to £950 at least. The warnings about unmatched transfers and missing purchases, where a handful on one exchange is a review and dozens across several sources is a computation. The disposals with a cost of nil, each a genuine airdrop or a purchase the software never saw. And the closing holdings the report believes you had on 5 April against what your wallets actually showed, because a report out by a whole coin has counted something twice or read a transfer as a sale.
Then two questions. Did the year include a liquidity pool, a lending protocol, a perpetual or a wrapped token? If yes, it is a reconciliation whatever the counts say. Is more than one year unfiled, or has HMRC written? If yes, it is the staged rebuild. The page on reports that owe tax in a losing year walks the same checks in detail, and the free review is where someone does them with you.
The fee beside the tax it corrects
Two worked files are already published on this site. The first is the report for the year to 5 April 2026 that showed a gain of £14,000. Three movements of ether to a hardware wallet had been read as sales and half an ether bought on an exchange that closed in 2023 carried a nil cost. Correcting those two places took the gain to £7,600. Against the £3,000 annual exempt amount on the published rates page, the report implied tax of £1,980 at 18% or £2,640 at 24%, and the corrected figure is £828 or £1,104, a difference of £1,152 or £1,536. That file has several sources, transfers read as sales and a closed platform, so its fee is the £950 computation.
The second is the single missing purchase. Two ether sold for £5,600 had been bought for £3,600, and the software priced them at nil. With other gains of £2,400 in the year, the report implied tax of £900 or £1,200 and the corrected figure is £252 or £336, a difference of £648 or £864. That history is one exchange with one fault. If the rest of the report is clean it is the £499 review, and the page on the warning shows how to clear that one fault yourself for nothing.
Those two pairs of numbers say nothing about your file, which is why the first look is free. The correction can also run the other way, because a report that misses a chain or reads a swap as a transfer understates the gain, and the fee is the same in either direction.
When you do not need anyone
If every source you used is connected, every transfer is matched at both ends, no disposal carries a nil cost you cannot explain, the method reads share pooling with the same day and 30 day rules, and the closing holdings match your wallets, the report is probably right. File it, keep the exports behind it, and hold the record in the shape CRYPTO10400 asks for, with the sterling value of each transaction on its date. The guide to crypto record keeping sets out the habit.
If your total gains for the year are inside the £3,000 annual exempt amount and you have no other reason to be in Self Assessment, there may be nothing to file at all. The gov.uk deadlines page puts the online return and the payment for the year to 5 April 2026 at 11.59pm on 31 January 2027.
What the wider market charges
Our page on what accountants charge for a tax return gathers the published figures. A standard Self Assessment return runs £150 to £400 plus VAT in two UK fee surveys updated in July and August 2026, and hourly rates run £50 to £150. For crypto, the market bands on our pricing page, gathered in September 2026, run from £99 to £349 for a flat rate filer who files your software report as it stands, £298 to £500 for a generalist bundle, £750 to £2,000 for a UK crypto tax firm on a single year, £1,200 to £2,500 for a heavy DeFi year, and £1,500 to £3,500 for a multi year catch up with a disclosure.
The three fees on this page sit inside those bands. Each is fixed before the work starts, so the hours a reconciliation needs are the firm’s risk and never yours. A quote that moves with the tax at stake is pricing your worry rather than the work.
How the engagement runs
You send the software report and the first look is free. The reply is a written fee the same working day. An engagement letter then sets out the scope, the fee and the date, and half the fee is paid on signing. The written position arrives within 15 working days of software access. You see the figures and approve them before anything is filed, and the balance is paid before the return goes to HMRC. UK tax only, and if the report is right as it stands you are told so and there is no fee.
Three fixed fees, quoted in writing before any work starts
One taxpayer, one tax year unless the line says otherwise. Written position within 15 working days of software access.
For an exchange-only history under about 5,000 trades where the software report is already built.£499
For several platforms, wallet transfers read as sales, duplicates, and one or two back years.£950
For DeFi, derivatives, high volume, or balances that do not tie.£1,750
Send your software report to zar@certifiedcryptoaccountant.com for a written fee the same working day, or start with the free review. Licensed and regulated by the AAT, licence 1010475.
Questions about the cost of fixing a report
How much does it cost to fix a crypto tax report in the UK?
One of three fixed fees. £499 to review and file an exchange-only report under about 5,000 trades that is already built, £950 for a computation across several platforms with transfers read as sales, duplicates and one or two back years, and £1,750 for a reconciliation where DeFi, derivatives, high volume or balances that do not tie are in the file. A rebuild of several years is staged from £3,450. The fee is set by what is wrong with the report and never by the tax at stake.
How much does a crypto accountant charge to review my Koinly report?
If the history is one or two exchanges under about 5,000 trades and the report is already built, the review and filing is £499. If the report carries transfers read as sales, nil costs or several platforms, the work is a £950 computation. The first look at the report is free and tells you which, and the fee is quoted in writing before any work starts.
Is the fee based on how much tax I owe?
No. The fee is set by the work in the report, which means the number of platforms and chains, the transfers that do not match, the disposals with a cost of nil, any DeFi or derivative positions, and the number of years. A corrected figure that goes up costs the same as one that goes down.
Can the fee change once the work has started?
No. The fee is quoted in writing before any work starts and that is the fee. The one staged engagement is the multi year rebuild, where the second stage is priced once the first is done, and that is said in the letter before you sign.
How long does it take to fix a crypto tax report?
The written position arrives within 15 working days of software access. The return for the year to 5 April 2026 is due online, with the payment, by 11.59pm on 31 January 2027, so a report sent in November or December leaves time to file without a rush.
Sources
Every figure on this page was checked against the source below on 11 November 2026.
- CRYPTO22100, Capital Gains Tax, what is a disposal. HM Revenue and Customs, checked 11 November 2026
- CRYPTO22150, Capital Gains Tax, allowable expenses. HM Revenue and Customs, checked 11 November 2026
- CRYPTO22200, Capital Gains Tax, pooling. HM Revenue and Customs, checked 11 November 2026
- CRYPTO10400, record keeping. HM Revenue and Customs, checked 11 November 2026
- Capital Gains Tax rates and annual tax-free allowances. HM Revenue and Customs, checked 11 November 2026
- Self Assessment tax returns, deadlines. GOV.UK, checked 11 November 2026
- Taxation of Chargeable Gains Act 1992, section 104. legislation.gov.uk, checked 11 November 2026
- Taxation of Chargeable Gains Act 1992, section 106A. legislation.gov.uk, checked 11 November 2026
- What accountants charge for a tax return in 2026 and why crypto changes the number. Certified Crypto Accountant, checked 11 November 2026
Fahad Zar
Crypto tax accountantAAT licensed 1010475
- AAT Licensed Accountant and MAAT, licence 1010475
- MSc Accounting and Finance, BPP University London
- Six years inside digital asset accounting, across several crypto tax firms
- Practises through Zar Enterprises Ltd, ICO registration ZC225094
- Supervised for anti-money laundering by the AAT
What matters to me is that the number on the return is true, whatever it turns out to be.
Whether this is worth a conversation
Where this stops being a reading job and starts being a hiring one.
- Your report has several platforms, transfers read as sales or nil costs, and you want a fixed fee in writing before the return is due on 31 January 2027
- You have had one quote that felt low and one that felt high and want to know which of them is pricing the actual work in your file
- The year had DeFi, derivatives or balances that do not tie, and you need the record that goes behind the figure as well as the figure
If every transfer is matched, no disposal carries a nil cost, the method reads share pooling and the closing holdings match your wallets, the report is probably right. File it yourself and keep the exports behind it. No fee is the right fee for that file.
If one of these is you, the first look costs nothing.
Read next
What accountants charge for a tax return in 2026
The published surveys, the market bands for crypto, and what moves a quote.
Reviewed 11 November 2026ExplainerYour report says you owe tax but you lost money
The five places a software report overstates the gain, with the £14,000 file corrected.
Reviewed 11 November 2026ExplainerMissing purchase history means a nil cost
Where the real cost hides and how to put it back yourself before paying anyone.
Reviewed 11 November 2026Deep guideCrypto reconciliation, the record behind the figure
What a transaction level reconciliation is and when a report needs one.
Reviewed 11 November 2026