Unclaimed capital losses expire after four years
Published 10 August 2026· Reviewed against gov.uk 25 August 2026· 4 min read·Capital gains tax
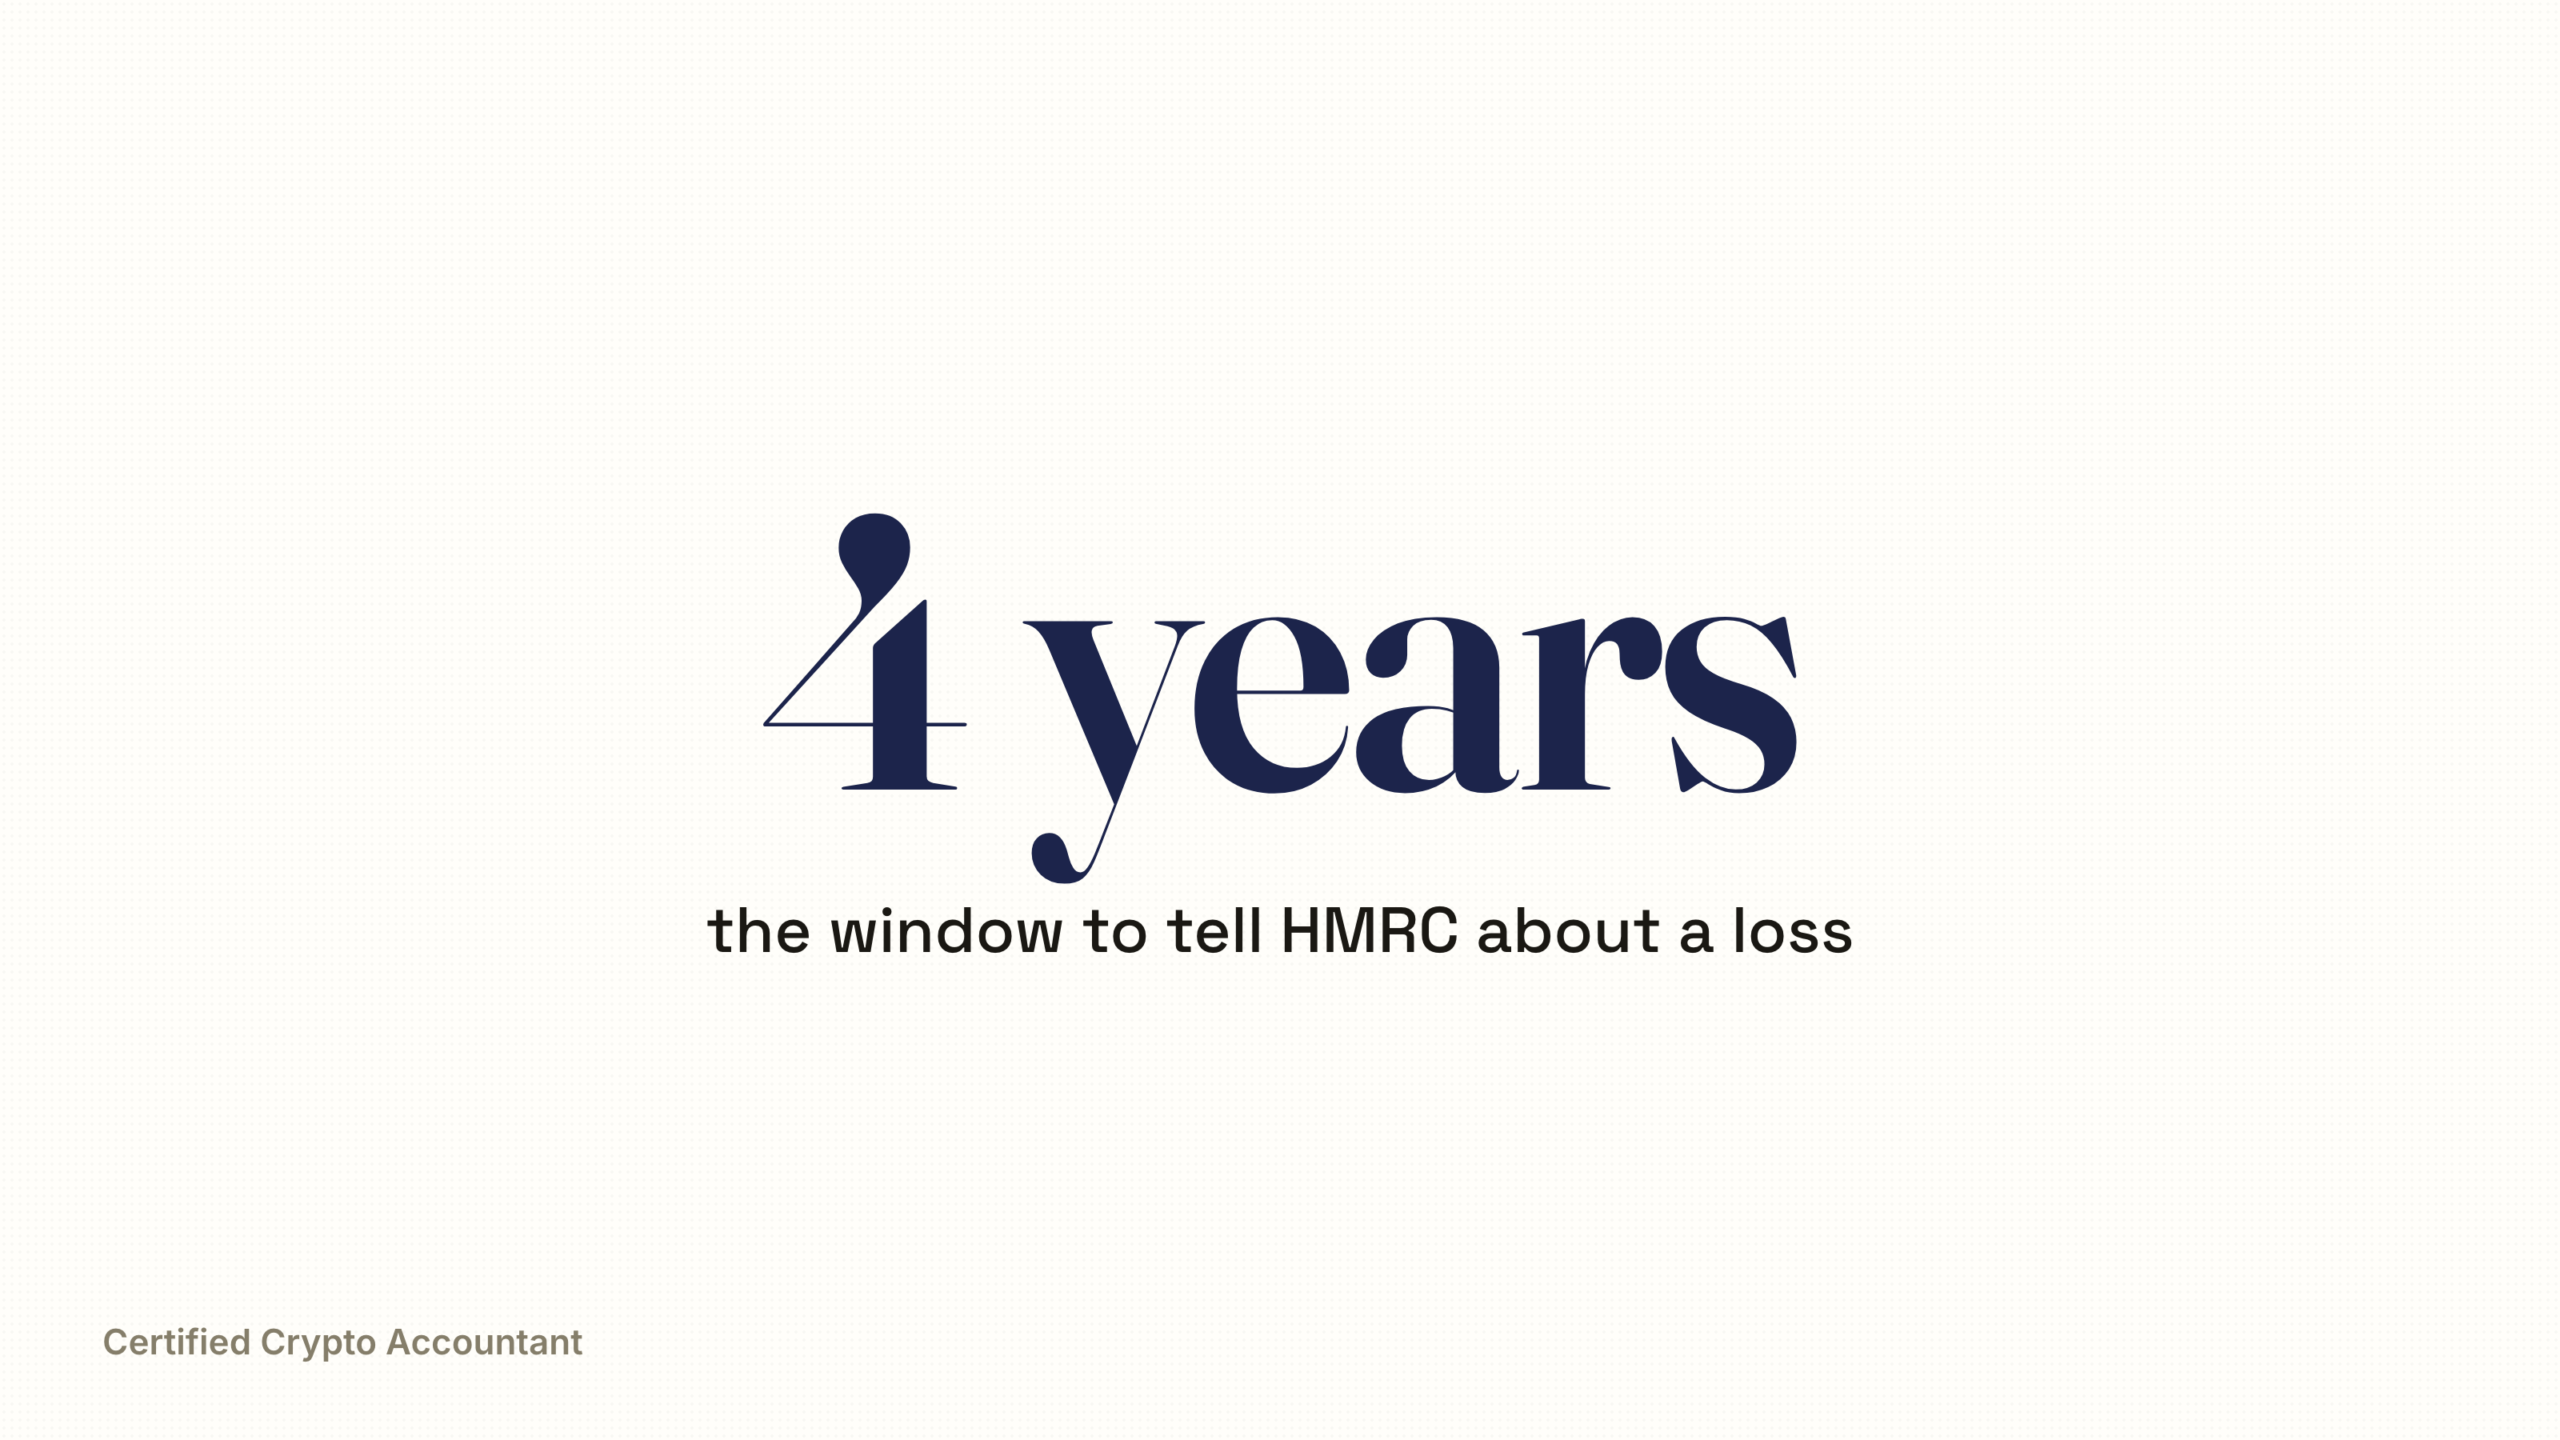
We reviewed a client’s records last month and found a £30,000 capital loss from a bad year, sitting in a spreadsheet, worth nothing. Not because losses are worthless, they are among the most valuable things in capital gains tax, but because a loss HMRC has never been told about does not exist in law. And the window for telling them closes four years after the end of the tax year the loss arose in.
That is the whole post in two sentences: losses must be claimed, and the clock is running on your old ones.
Why claiming is not automatic
The statute is blunt. Under section 16(2A) of the Taxation of Chargeable Gains Act 1992, a loss is not allowable unless it has been quantified and notified to HMRC. Selling at a loss does nothing by itself. Recording it in your portfolio app does nothing. The notification, normally through the capital gains pages of your return, is what converts a bad trade into a tax asset.
The time limit comes from the general claims rule, four years from the end of the relevant tax year. A loss made in 2022 to 2023 must be claimed by 5 April 2027. After that it is gone, permanently, no matter how well documented. HMRC’s losses helpsheet HS227 covers the machinery.
What a claimed loss is worth
Once claimed, losses work in a fixed order. They offset gains in the same tax year first, and this part is compulsory, even where the allowance would have covered those gains anyway. Whatever is left carries forward indefinitely, and carried losses are applied with more finesse: only enough to bring future gains down to the annual allowance, so nothing gets wasted covering gains that were already tax free.
At current rates the arithmetic is plain. A £30,000 loss set against gains taxed at 24% is £7,200 that stays yours. Losses do not expire once claimed, so a crash year properly banked can shelter a recovery years later, which is precisely what loss harvesting builds on.
The crypto-specific wrinkles
Two matter. The 30 day rule first: sell at a loss and buy the same token back within 30 days and the loss gets matched against your buyback rather than banked, the mechanics HMRC sets out in its pooling guidance. The loss you planned in a dip-buying December can evaporate this way.
Second, tokens that died rather than fell. Where an asset has become worthless you can make a negligible value claim, which treats it as sold and reacquired at nothing, crystallising the loss without finding a buyer for a dead coin. Rug pulls and collapsed exchanges each have their own routes, which our guide to stolen and lost crypto walks through, because theft and worthlessness are treated differently and the difference decides whether relief exists at all.
How to actually claim
In Self Assessment, losses go on the capital gains pages with your computations, claimed in the same breath as the year’s gains are reported. Not filing that year because nothing was owed is the classic mistake, the return was optional but the loss claim needed a vehicle. Outside Self Assessment, or for old years inside the four year window, a standalone written claim to HMRC quantifying the loss does the job. Either way the claim needs numbers behind it, acquisition cost and disposal value, which for crypto means the reconciliation work that underpins the whole return.
Loss questions
Which years can I still claim for?
Count back four years from the end of the tax year of the loss. Right now, losses from 2022 to 2023 onward are still claimable, and each 5 April another year falls off the edge.
Do losses offset income?
Capital losses offset capital gains only, with narrow statutory exceptions. The trader-status argument people reach for in bad years to get at income relief almost never succeeds, as our badges of trade guide explains.
Can I choose not to use losses this year?
Same-year losses, no, they apply automatically against that year’s gains. Carried-forward losses self-regulate, used only down to the allowance, so they are never wasted.
My loss is on a coin that no longer trades. Claimable?
Through a negligible value claim, yes, if the asset is genuinely worthless while you still own it. Documentation of what it was worth and what happened carries the claim.
If there is a bad year anywhere in your last four, it is worth an hour to find out what it is worth before a deadline decides for you. That is exactly the kind of thing our free review turns up.
Sources
Every figure on this page was checked against the source below on 25 August 2026.
- Section 16(2A) of the Taxation of Chargeable Gains Act 1992. legislation.gov.uk, checked 25 August 2026
- Four years from the end of the relevant tax year. legislation.gov.uk, checked 25 August 2026
- Losses helpsheet HS227. GOV.UK, checked 25 August 2026
- Its pooling guidance. GOV.UK, checked 25 August 2026
Fahad Zar
Crypto tax accountantAAT licensed 1010475
- AAT Licensed Accountant and MAAT, licence 1010475
- MSc Accounting and Finance, BPP University London
- Six years inside digital asset accounting, across several crypto tax firms
- Practises through Zar Enterprises Ltd, ICO registration ZC225094
- Supervised for anti-money laundering by the AAT
What matters to me is that the number on the return is true, whatever it turns out to be.
Whether this is worth a conversation
Most people who read this page do not need an accountant. A few do.
- Your gains are near the £3,000 line
- You have swapped tokens and doubt the numbers
- You have old losses nobody ever claimed
If you sold one holding once and the figures are plain, file it yourself. Paying someone to check arithmetic you can do is not a service.
If one of these is you, the first look costs nothing.
Read next
Your capital gains tax allowance for 2026 to 2027
£3,000 per person, resets each April, never carries forward. How the annual exempt amount works, the spouse doubling,…
Reviewed 25 Aug 2026ExplainerHow to report capital gains on your Self Assessment
Gains go on the SA108, property runs on its own 60 day track, and proceeds over £50,000 mean reporting even with no tax…
Reviewed 25 Aug 2026ExplainerCapital gains tax on shares and the 30 day trap
Share matching rules define your cost, the 30 day rule rewrites rebuys, and accumulation funds hide base cost. What…
Reviewed 25 Aug 2026ExplainerCapital gains tax treats a gift as a sale you were never paid for
Gifting an asset is a disposal at market value, so tax can fall due when no money changed hands. The spouse and charity…
Reviewed 25 Aug 2026